TVS Emerald Avalon EMI calculator
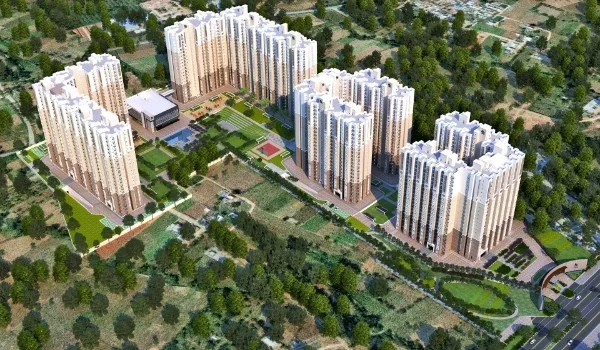
The TVS Emerald Avalon EMI calculator is a financial tool that computes your exact monthly home loan payment and total interest cost for apartments inside this 12.44-acre project on Pallavaram-Thoraipakkam Radial Road. This residential community features 1,035 homes across 10 high-rise towers of 15 floors each, with base prices starting at ₹1.20 Crore for 2 BHK flats (965 to 1,245 sq. ft.) and moving higher for 3 BHK (1,540 to 1,700 sq. ft.) and 4 BHK duplex units (2,440 to 2,590 sq. ft.).
Using this tool helps buyers check their initial 20% down payment needs and compare prevailing bank rates between 8.40% and 9.25% across 10 to 30 years. It gives home seekers a clear look at their bank payouts each month, so their personal savings remain secure as building work moves toward possession in 2029.
Planning your monthly budget early keeps you ready for bank disbursements as each construction stage is reached. It also stops unexpected financial pressure from affecting your regular household lifestyle.
Unit Prices and Monthly EMI Estimates Across Configurations
Most commercial banks can lend up to 80% of the flat price. For a base 2 BHK, the starting EMI is around ₹83,313 per month at an 8.50% interest rate for 20 years. Buyers need to pay the remaining 20% as a down payment from their own savings before the bank releases the home loan.
The numbers below give you a clear look at estimated monthly instalments across all standard configurations available in the project.
| Configuration | Built-up Area (sq. ft.) | Base Price | 20% Down Payment | 80% Loan Amount | Monthly EMI (20-Year Loan) | Monthly EMI (30-Year Loan) |
|---|---|---|---|---|---|---|
| 2 BHK (Compact) | 965 – 1,080 | ₹1,20,00,000 | ₹24,00,000 | ₹96,00,000 | ₹83,313 | ₹73,816 |
| 2 BHK (Large) | 1,150 – 1,245 | ₹1,35,00,000 | ₹27,00,000 | ₹1,08,00,000 | ₹93,728 | ₹83,043 |
| 3 BHK (Standard) | 1,540 – 1,620 | ₹1,75,00,000 | ₹35,00,000 | ₹1,40,00,000 | ₹1,21,498 | ₹1,07,649 |
| 3 BHK (Large) | 1,650 – 1,700 | ₹1,95,00,000 | ₹39,00,000 | ₹1,56,00,000 | ₹1,35,384 | ₹1,19,951 |
| 4 BHK Duplex | 2,440 – 2,590 | ₹2,95,00,000 | ₹59,00,000 | ₹2,36,00,000 | ₹2,04,815 | ₹1,81,466 |
How the EMI Calculator Formula Computes Your Monthly Payment
The EMI calculator uses a standard reducing-balance math formula that splits every monthly payment into bank interest and loan principal reduction. It applies this equation automatically to give you an instant result:
EMI = [P × r × (1 + r)^n] / [(1 + r)^n - 1]
- EMI = Equated Monthly Instalment
- P = Principal loan amount
- r = Monthly interest rate (Annual interest rate divided by 12, then divided by 100)
- n = Loan tenure in number of months
- ^n = Raised to the power of n
In the first 5 years of your loan, over 65% of each EMI goes purely toward paying interest to the bank. As the years roll on, the interest portion drops each month, and more of your money goes toward clearing the actual principal balance.
Total Interest Outflow Across 15, 20, and 30-Year Loan Tenures
An ₹80,00,000 home loan at 8.50% costs ₹61,80,220 in total interest over a 15-year term, but that interest cost jumps to ₹1,41,44,680 over a 30-year term. Picking the right loan tenure is about finding a healthy middle ground between a comfortable monthly EMI and low lifetime bank interest.
- 15-Year Term: Your monthly EMI is ₹78,779, keeping your lifetime interest bill low at ₹61.80 Lakh. This plan works best if your family income allows higher monthly payments.
- 20-Year Term: Your monthly payment drops to ₹69,426, while total interest climbs to ₹86.62 Lakh. This remains the most popular choice for salaried buyers looking for steady cash flow.
- 30-Year Term: Your monthly payment falls to a low ₹61,513, but total bank interest shoots up to ₹1.41 Crore. You end up paying back more than double what you originally borrowed.
Pre-EMI vs Full EMI Payments During 2029 Project Construction
With Pre-EMI, you pay interest only on the loan amount the bank has released to the builder until the planned 2029 handover. Since TVS Emerald Avalon is under construction, banks release the home loan in stages as the work moves ahead.
- Pre-EMI Choice: You pay interest only on the loan amount the bank has released. For example, if the bank releases ₹30 Lakh, you pay interest only on that amount. This keeps your monthly payment lower until you get the keys.
- Full EMI Choice: You start paying the full EMI from the beginning. This covers both the loan principal and interest. It reduces your loan balance faster and can lower the total interest you pay before moving in.
How Yearly Part-Prepayments Cut Your Total Loan Tenure
Paying one extra EMI of ₹83,313 every year cuts a 20-year home loan by almost 4 years and saves over ₹18 Lakh in interest. Prepayments go 100% toward your principal debt, shrinking your remaining balance immediately.
- Use Annual Bonuses: Put job bonuses, tax refunds, or dividend income straight toward your principal balance each year.
- No Penalty on Floating Loans: Reserve Bank of India (RBI) rules ensure that floating-rate individual home loans have zero penalty fees for prepayment or early loan closure.
- Reset Your Tenure: Whenever you make a part-payment, ask your bank to shorten your loan tenure instead of lowering your monthly EMI to maximize your interest savings.
Frequently Asked Questions
The lowest monthly payment is about ₹73,816 for a base 2 BHK unit priced at ₹1.20 Crore, assuming an 80% loan at 8.50% interest over 30 years.
Lenders ask for a 20% down payment from your own funds, which means about ₹24 Lakh for a 2 BHK, ₹35 Lakh for a 3 BHK, and ₹59 Lakh for a 4 BHK duplex.
No, the EMI calculator only computes the bank loan amount, meaning the 7% registration fee, 2% stamp duty, and 5% GST must be paid from separate cash savings.
On an ₹80 Lakh loan over 20 years, a 0.50% rate drop from 8.50% to 8.00% lowers your monthly EMI by about ₹2,536 and saves over ₹6.08 Lakh in lifetime interest.
Yes, most home loan lenders let borrowers switch to full principal-plus-interest EMIs during the construction stage to speed up loan repayment before possession in 2029.