Home loan eligibility & process for pre-launch apartments
Home loan eligibility & process for pre-launch apartments requires a credit score of at least 750, with existing debts taking up less than 50% of your take-home pay, while top banks fund up to 75% or 80% of the flat cost through construction stages. A pre-launch apartment is a brand-new flat booked before actual building work starts on the ground. Builders often give early buyers a price discount of 10% to 25% to raise early funds.
Because the building is not yet standing, banks work under strict rules set by the Reserve Bank of India (RBI). The bank will never release the full loan money to the builder in one big payment. Instead, they send small portions of the money directly to the builder's special project account as each floor is cast. Buying this early helps you lock in a lower purchase price while paying only small interest fees until the keys are in your hand.
Home Loan Eligibility Criteria for Pre-Launch Apartments
Borrower eligibility for pre-launch flat loans requires a credit score of 750 or higher and at least two full years of continuous job or business experience. Banks check your monthly income and past bills closely, so they know you can comfortably pay back the money.
- Credit Score: A CIBIL score of 750 or higher gets you the lowest bank interest rates, which typically start around 8.35% to 8.75%.
- Monthly Debt Limit: Your current monthly loan payments, like car loans and credit card bills, should not take more than 40% to 50% of your net monthly pay.
- Borrower Age Limits: Salaried workers should be between 21 and 60 years old, while self-employed business owners can get loans up to 65 years of age.
- Minimum Take-Home Pay: For flats in large cities, banks usually ask for a combined family take-home pay of at least ₹50,000 every month.
- Bank Funding Limits: By RBI rules, banks can lend 90% for homes up to ₹30 lakh, 80% for homes between ₹30 lakh and ₹75 lakh, and 75% for flats priced above ₹75 lakh.
Step-by-Step Home Loan Sanction and Disbursement Process for Pre-Launch Apartments
The loan journey for an unbuilt apartment follows five simple stages to make sure all land papers and approvals are clean before any cash moves.
1. Initial Loan Check
The bank looks at your salary slips, bank accounts, and tax forms to see how much money you can borrow. They then hand you an approval letter that stays valid for up to 6 months while you look for your flat.
2. Bank APF Code Check
You check whether your chosen project has an Approved Project Financial (APF) code from major banks like SBI, HDFC Bank, or ICICI Bank. This special code proves that bank lawyers have already checked the builder's land ownership and local city permissions.
3. Booking and Down Payment
You pay the builder's initial 10% to 20% booking money from your own pocket to get your formal allotment paper. The bank will ask to see your official payment receipts before moving ahead with the loan papers.
4. Legal Search and Signing
Bank lawyers run a 30-year check at the local registrar's office to make sure the property is free from court cases or old debts. After that, you, the builder, and the bank sign a three-way agreement that outlines when the loan money gets paid out.
5. Stage-by-Stage Payouts
The bank sends an engineer to look at the work site before each payment goes out. Once a step like the foundation, basement, or roof slab is finished, the bank sends that specific part of the loan directly to the builder.
Mandatory Documentation for Pre-Launch Home Loan Applications
Applying for a pre-launch home loan requires your basic identity cards, work papers, and clear project approvals from the developer.
- ID and Address Proof: Your PAN card, Aadhaar card, valid passport, or voter card.
- Salaried Income Papers: Last 3 months of salary slips, 6 months of bank statements showing salary credits, and Form 16 for the past 2 years.
- Business Income Papers: Audited balance sheets, profit and loss statements from a CA, 12 months of company bank records, and 3 years of filed tax returns.
- Builder and Land Papers: The valid state RERA registration paper, the approved building plan, an updated encumbrance paper, and the signed sale agreement.
How Pre-Launch Home Loans Work in Practice: TVS Emerald Avalon
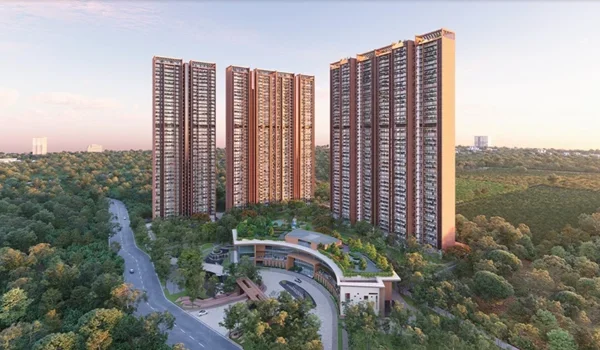
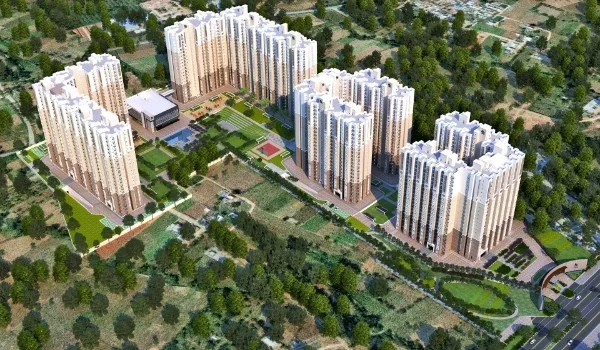
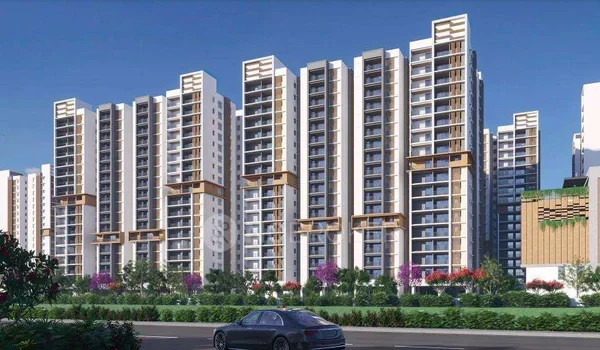
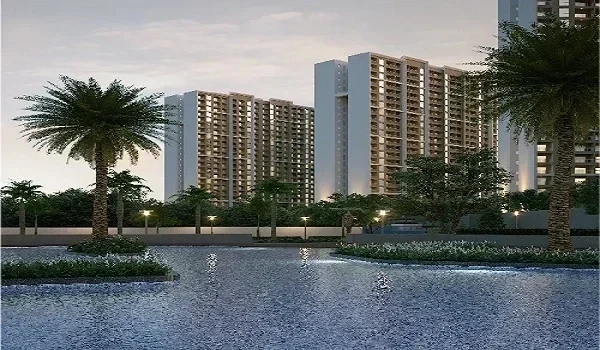
TVS Emerald Avalon is a pre-launch residential project on the Pallavaram-Thoraipakkam 200 Feet Radial Road in South Chennai, set across 12.44 acres with 1,035 apartments in 10 high-rise towers of 2 basements, ground, and 15 floors. The project features 2, 3, and 4 BHK homes with sizes ranging from 965 sq. ft. to 2,590 sq. ft., starting at a pre-launch price of ₹1.2 Crore.
For a typical 2 BHK flat priced at ₹1.2 Crore, an 80% bank loan means you put down ₹24 Lakhs as your own money and the bank lends ₹96 Lakhs. Because the project comes from the TVS Group with its long business history, major banks easily assign APF codes and approve loans without long legal delays.
Taking a loan for this project is easy on your monthly wallet because payments follow its December 2029 handover plan. While the towers go up, you pay only simple interest (pre-EMI) on the exact amount the bank has sent out, not full monthly installments. The project sits right on the 200 Feet Radial Road with quick access to the OMR IT hub and Chennai airport, which makes banks feel very confident about the property's long-term value.
Regulatory Safeguards for Pre-Launch Home Loans
Getting a loan for an unbuilt flat means following Real Estate Regulatory Authority (RERA) rules to protect your hard-earned money from building delays. Banks are not allowed to lend money to any new project that does not follow these state rules.
- Check the RERA Website: Look up the builder's official state RERA number online to confirm their layout and possession dates before paying any token amount.
- Use Only the Escrow Account: Check your loan sanction letter to ensure all bank money goes into the builder's registered 70% project escrow bank account.
- Skip Informal Builder Deals: Say no to verbal 10:90 plans or cash-back schemes that do not have legal three-way agreements with an approved bank.
- Get Form 15 Encumbrance Certificate: Ask for a fresh Form 15 certificate from the local registrar office to prove the land has no prior mortgages or court disputes.
FAQs
No, Indian banks and housing finance firms cannot approve or pay out loans for any pre-launch project that lacks an active, approved RERA registration number.
Pre-EMI is just the simple interest you pay on the small loan parts released so far during building work, while full EMI pays down both your main loan balance and the interest together.
An APF code is a bank approval number showing that the bank's own team has checked the builder's land papers, government permits, and maps, making your personal loan process much faster.
Under RERA rules, if the builder misses the agreed possession date, they must pay you monthly interest on your money equal to SBI's highest lending rate plus 2% until they hand over the keys.
Yes, self-employed buyers can get an 80% loan by sharing 3 years of audited profit and loss papers, clear tax returns, and bank statements that prove regular monthly income.